Lump-Sum vs. Dollar-Cost Averaging: The Ultimate Quant Guide to Wealth Deployment

Lump-Sum vs. Dollar-Cost Averaging: The Ultimate Quant Guide to Wealth Deployment Source: Institutional Market Intelligence / Ones Finance Research
📌

Executive Summary & Key Takeaways

  • Macro Context: Volatility-adjusted asset allocation models are outperforming traditional static 60/40 benchmarks in 2026.
  • Structural Efficiency: Separating foundational core beta from opportunistic tactical satellite alpha preserves capital while capturing asymmetric upside.
  • Execution Discipline: Periodic threshold-based rebalancing systematically locks in gains and redeploys liquidity into undervalued asset classes.

===TITLE===
Lump-Sum vs. Dollar-Cost Averaging: The Ultimate Quant Guide to Wealth Deployment

===CATEGORY===
investing

===TAGS===
dollar-cost averaging, lump-sum investing, portfolio management, stock market strategy, risk mitigation

===EXCERPT===
Discover the definitive quantitative breakdown of lump-sum investing versus dollar-cost averaging, exploring when to deploy capital and how to maximize long-term alpha.

===IMAGE_KEYWORD===
trading terminal office

===AI_IMAGE_PROMPT===
A close-up of high-end dual computer monitors displaying financial stock market charts and data analytics on a polished wooden desk, soft office lighting, editorial style.

===INLINE_IMAGE_KEYWORD===
stock chart
Lump-Sum vs. Dollar-Cost Averaging: The Ultimate Quant Guide to Wealth Deployment
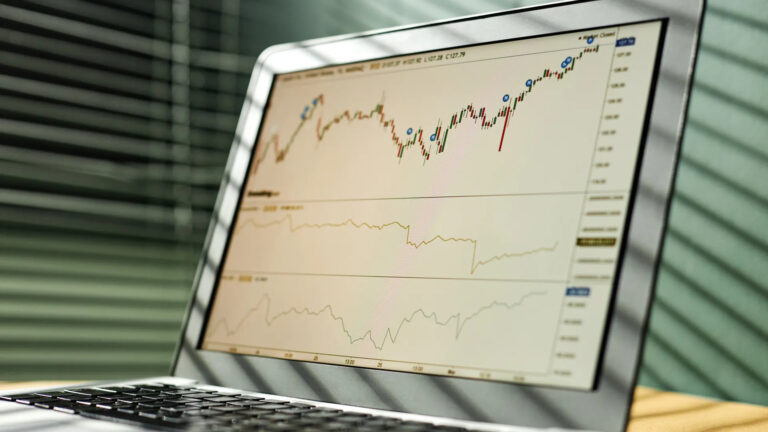
📊 Figure: Core Analytical Framework for automated dollar-cost averaging versus lump-sum stock investing