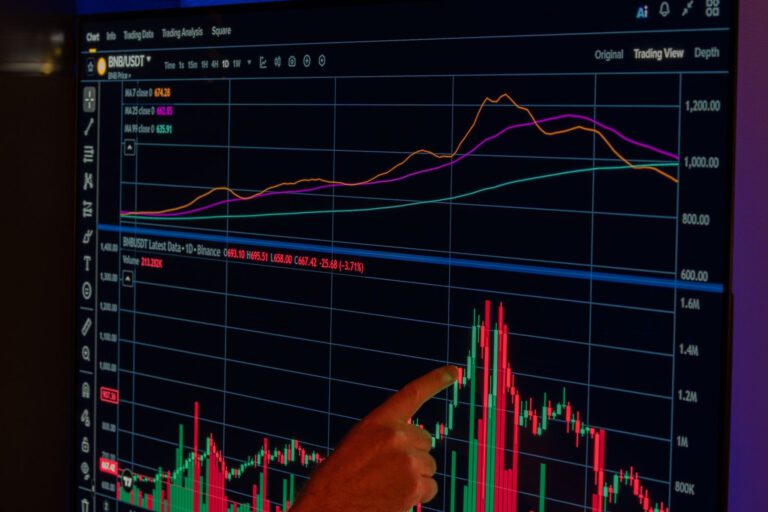
For decades, institutional capital and high-frequency trading (HFT) powerhouses have dominated the world’s financial exchanges using complex mathematical models, high-speed fiber-optic connections, and automated execution engines. Wall Street didn’t win by guessing market direction; it won by systematic elimination of human emotion. Today, thanks to the democratization of financial data, cloud computing infrastructure, and commission-free application programming interfaces (APIs), retail investors have unprecedented access to the tools of modern quantitative finance. Transitioning from discretionary, gut-feel trading to algorithmic precision is no longer reserved for multi-billion-dollar hedge funds.
However, unlocking the power of algorithmic trading requires more than downloading a Python script or copying a moving-average crossover from an internet forum. Retail traders must understand the fundamental pillars of quantitative design: hypothesis generation, rigorous historical backtesting, risk parameterization, and execution infrastructure. At Ones Finance, we believe that understanding these mechanics is essential for any modern investor seeking sustainable edge in increasingly volatile markets.
Key Takeaways for Retail Quants
- Systematic Discipline: Algorithms eliminate psychological pitfalls like FOMO (fear of missing out), panic selling, and revenge trading.
- Backtesting Realities: Past performance does not guarantee future results; understanding overfitting and data snooping bias is vital.
- Execution Matters: Slippage, latency, and brokerage commission fees can quickly erode the theoretical profits of high-frequency retail strategies.
- Risk Management First: Position sizing and dynamic stop-losses must be hardcoded into every quantitative model before deployment.
1. The Evolution: From Discretionary Guesswork to Quantitative Logic
Discretionary trading relies on human intuition, chart patterns, macroeconomic news interpretations, and psychological fortitude. Unfortunately, behavioral economics consistently proves that human beings are poorly wired for financial markets. We suffer from confirmation bias, anchor our prices to arbitrary historical highs, and panic during sudden market corrections.
Quantitative trading transforms investment ideas into explicit, mathematical rules. Instead of asking, “Do I think Apple stock looks cheap today?” a quantitative trader asks, “What is the historical statistical probability of a positive 5-day return when Apple’s 14-day Relative Strength Index (RSI) drops below 30 while trading below its 200-day simple moving average?”
“In quantitative finance, if a trading thesis cannot be explicitly programmed into an if-then logical statement, it does not exist.” — Ones Finance Quantitative Desk
By shifting from subjective observation to objective measurement, retail investors can evaluate trading ideas across decades of historical market data in mere seconds.